Prepared for indoor playground owners comparing quote readiness
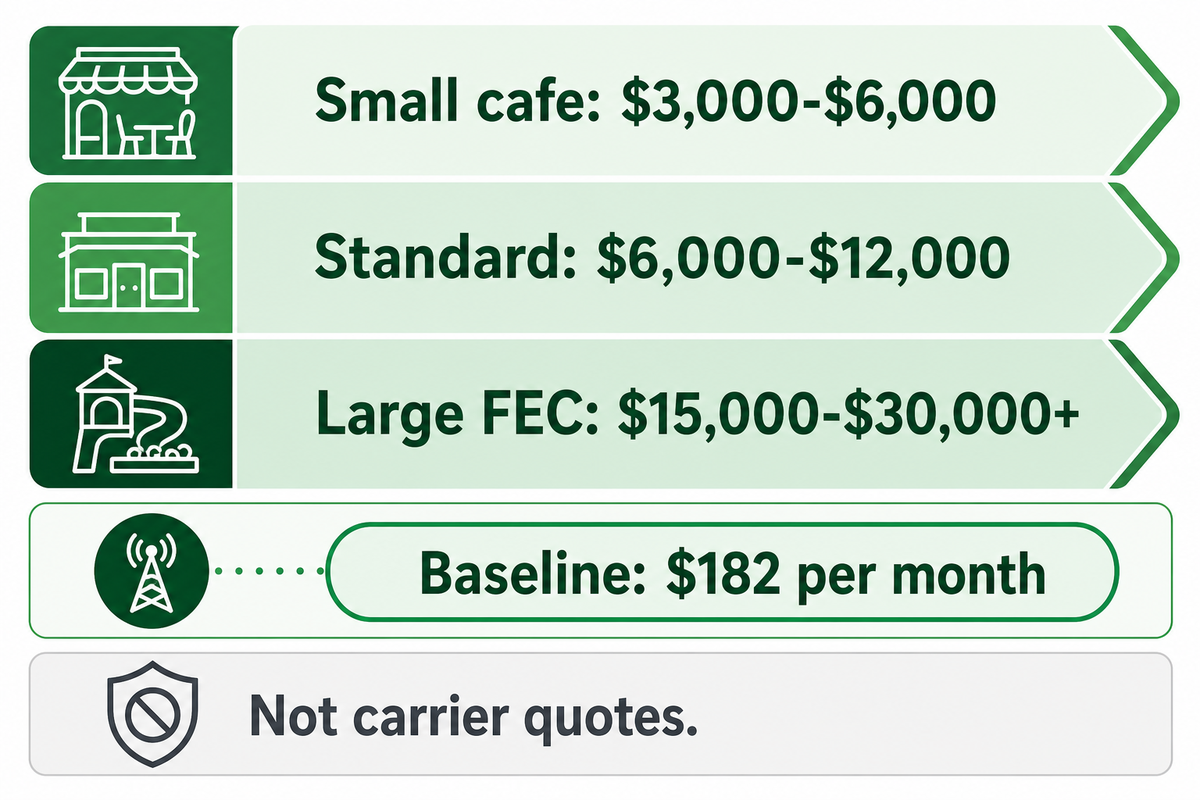
Indoor playground insurance cost is best planned as an annual policy stack, not one flat fee. For early budgeting, Dreamland uses planning bands of about $3,000 to $6,000 for a small soft-play cafe, $6,000 to $12,000 for a standard indoor playground, and an estimated $15,000+ for a larger family entertainment center; these are not carrier quotes or published market averages.
Dreamland Playground is not an insurance carrier or broker. This guide turns public insurance cost data, underwriter factors, and Dreamland equipment-file tools into a quote-readiness framework so owners know what to prepare before asking a licensed broker or carrier for final premiums.
Fast Answer: What Annual Premium Should Owners Budget?
Dreamland uses the following estimated ranges only for pre-quote budgeting: $3,000 to $6,000 per year for a small play cafe, $6,000 to $12,000 for a standard indoor playground, and an estimated $15,000 to $30,000+ for a larger family entertainment center with higher-risk attractions. These bands are an internal planning model, not carrier quotes or published market averages. They are derived from public insurance averages, the policies an owner usually needs, venue size, attraction risk, payroll, property value, and underwriting documentation.
Public baseline data starts with Insureon, which lists average monthly costs for small indoor playground businesses of $45 for general liability, $83 for a business owner policy, and $54 for workers compensation. That reported three-policy set gives a calculated reference total of $182 per month, or about $2,184 per year, before higher limits, property values, umbrella coverage, special attractions, state requirements, or claims history change the price. Treat it as a lower reference point, not as a complete quote for every play center.
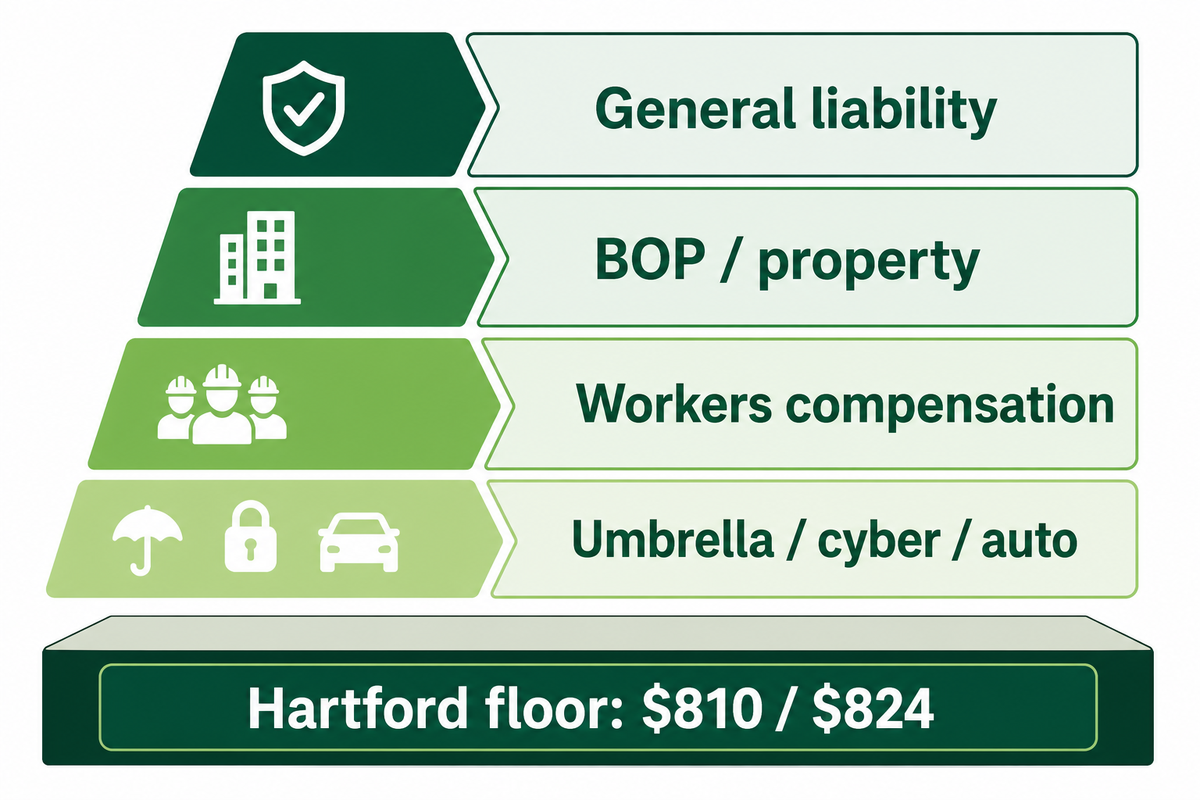
4-Layer Premium Stack
Base policies set the floor. Facility size, attraction mix, payroll, and documentation quality decide whether the owner stays near the floor or move into a higher underwriting band.
Annual Premiums by Size: A Planning Table
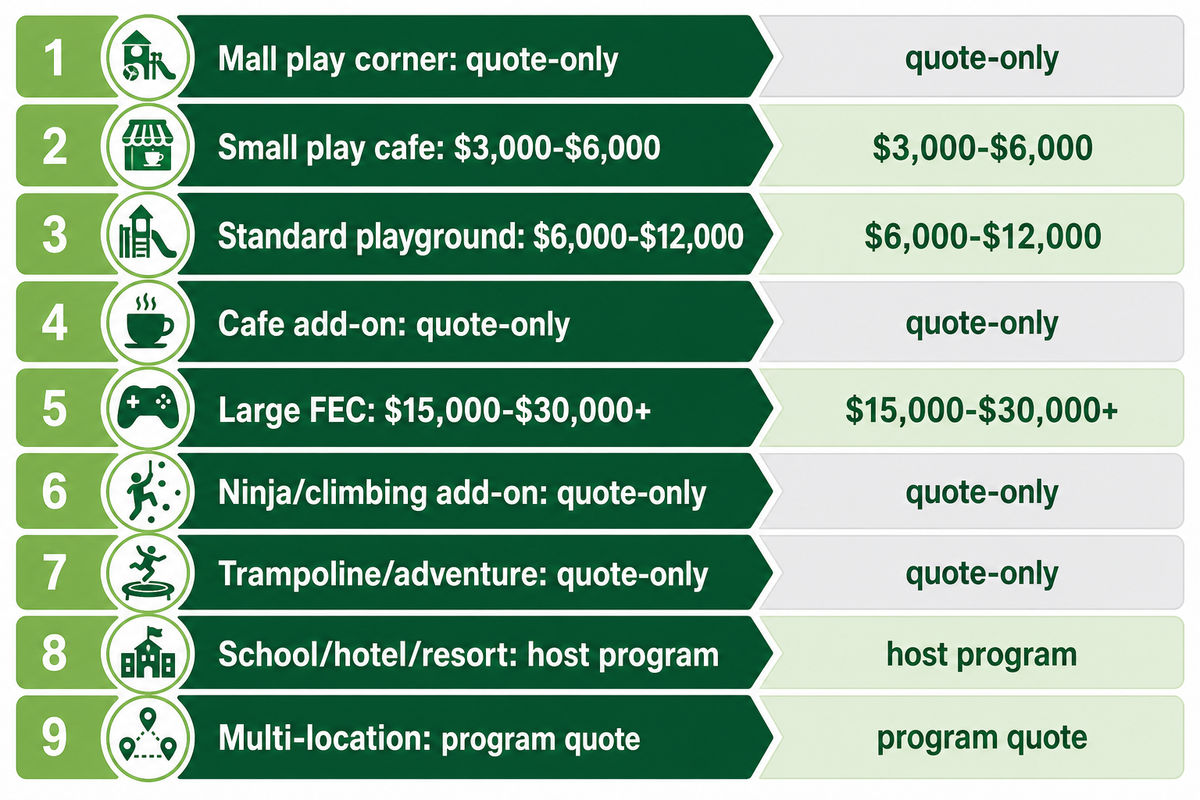
Owners still need carrier quotes, but they also need a first-pass budget before signing a lease or ordering equipment. This table separates facility size from attraction risk, because square footage alone does not explain the premium. Use these Dreamland bands for financial modeling only; brokers and carriers must confirm the actual premium.
Venue type
Typical size signal
Annual premium planning band
What usually moves it
Mall play corner
Compact soft-play zone inside a mall, hotel, or store
Quote-only; compare against the small play cafe band
Landlord limits, shared premises rules, equipment value, supervision plan
Small play cafe
Toddler soft play, party room, light food service
Planning estimate: $3,000-$6,000
BOP, general liability, small payroll, property value, landlord limits
Standard indoor playground
Soft contained play, slides, climbing, party traffic
Planning estimate: $6,000-$12,000
Higher revenue, more employees, equipment replacement value, incident logs
Standard playground plus cafe
Soft play with food counter, parties, and longer dwell time
Quote-only; may sit above the standard playground band
Food service, cleaning process, staff role split, product liability questions
Large family entertainment center
Ninja, climbing, arcade, cafe, group events, larger payroll
Planning estimate: $15,000-$30,000+
Attraction schedule, umbrella limits, workers compensation, food service, claims history
Ninja or climbing add-on center
Obstacle lanes, climbing walls, timed races, elevated movement
Quote-only; often above soft-play-only pricing
Fall zones, staff training, supervision ratio, waiver and incident records
Guest or student play space with controlled access
Quote-only under the host property program
Host policy wording, public access, age range, inspection routine
Multi-location or franchise rollout
Several sites using similar layouts, documents, and operating rules
Program quote; schedule each location separately
Loss history, consistent training, certificate needs, location-by-location payroll
Use the size bands as a sanity check. If a 2,000-square-foot toddler cafe is quoted like a trampoline park, ask which attraction, limit, or prior-loss assumption drove the price. If a 12,000-square-foot family entertainment center receives a very low quote, check whether the policy excludes attractions the floor actually has.
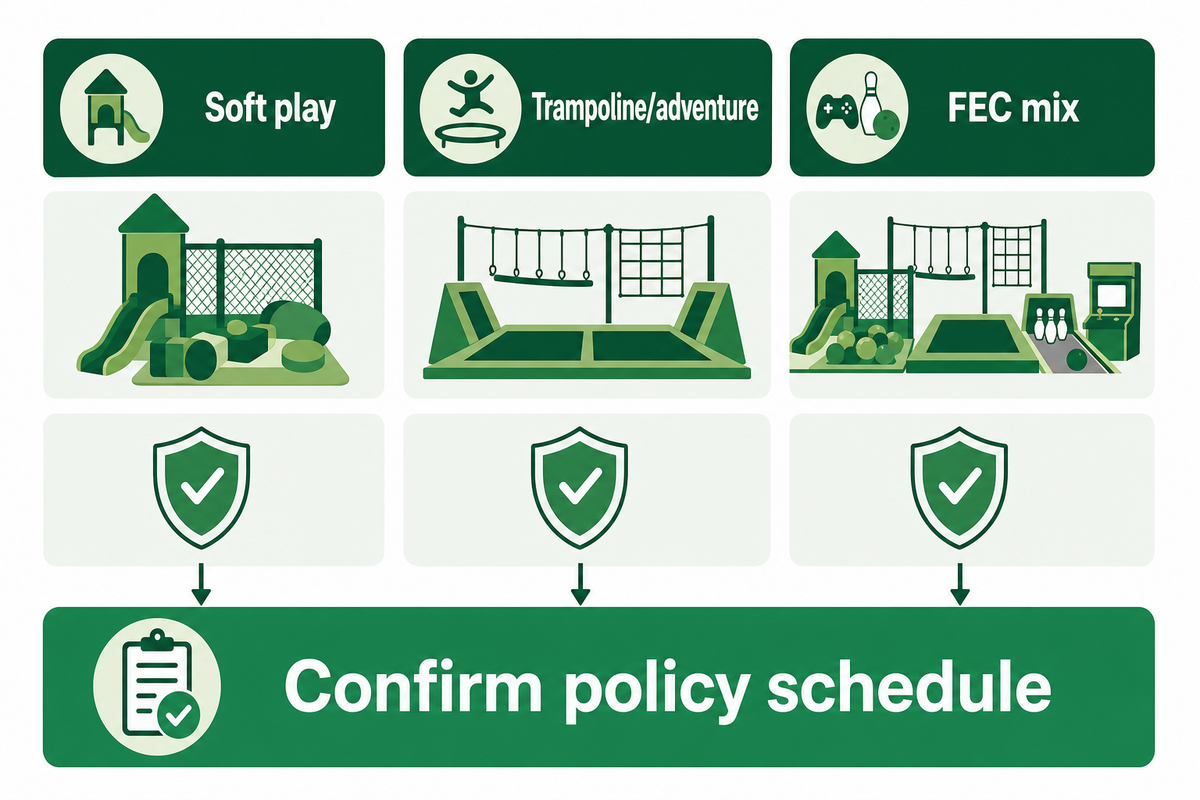
Keep Soft Play, Trampoline Parks, and FECs Separate
Soft-play indoor playgrounds, trampoline parks, and broad family entertainment centers can all appear in insurance conversations, but they aren’t the same risk. Soft-play facilities usually center on contained play structures, slides, toddler zones, and birthday rooms. Trampoline or adventure-heavy venues add higher-motion attractions such as trampoline courts, ninja lanes, ropes, climbing, or elevated obstacles. Family entertainment centers may combine soft play with arcade, cafe, parties, school groups, and multiple activity zones.
This distinction matters because a low quote for one product family may exclude another. When comparing annual premiums by size, owners should list every attraction exactly as it will open on the floor and ask the broker to confirm that the policy schedule names the real operation.
What Policies Are Usually in the Cost Stack?
Base coverage usually starts with general liability, a business owner policy or commercial property coverage, and workers compensation when employees are on payroll. Many venues also need commercial auto, cyber coverage for booking and waiver systems, umbrella or excess liability, and special endorsements for food service, events, or higher-risk attractions.
On its 2026 general liability cost page, The Hartford gives a broader all-industries small-business reference point: its customers average about $810 per year, and a $1 million liability policy averages about $824 per year. Those figures are useful as a floor, not as play-center-specific pricing, because children, active play, group events, equipment, and visitor volume change the exposure.
Why Two Similar Playgrounds Get Different Premiums
There’s more to underwriting than just the area of the space. Some of Insureon’s specified indoor playground premium determinants include service type, revenue, number of employees, cost/condition of equipment, site, safety measures, limitations, deductibles, and history of claims. Hartford includes factors such as the business address, number of years in operation, coverage options (limits and deductibles), type of operation and, finally, claims experience.
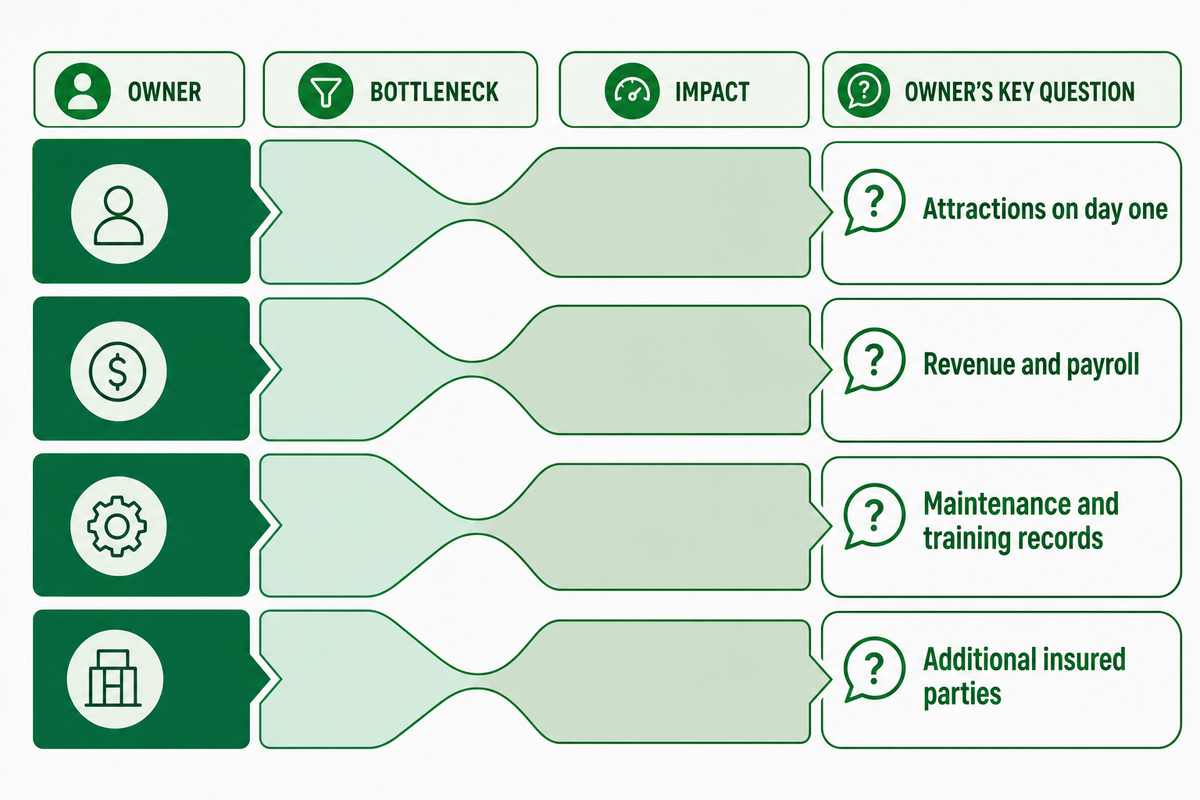
Hidden bottleneck map
Owner: Does the quote include every attraction that will open on day one?
Finance: Does the annual premium assume realistic revenue and payroll?
Operations: Can staff produce maintenance logs, incident reports, and training records for any date?
Landlord or mall: Does the certificate name the correct additional insured parties?
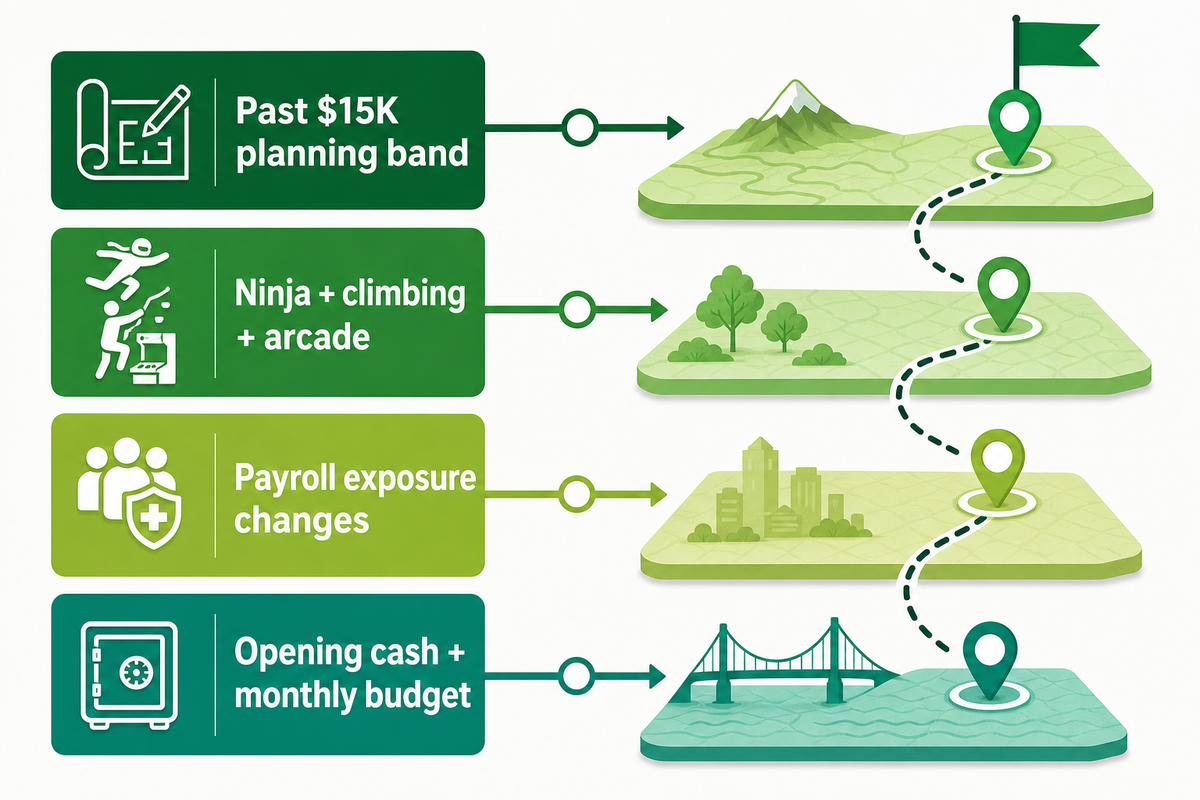
Why a Large FEC Can Move Past $15K
Large family entertainment centers are rarely just bigger soft-play rooms. They may combine soft-contained play, ninja elements, climbing, arcade games, party bookings, school groups, cafe service, and a larger staff. Each layer gives the underwriter a new way to ask whether the policy schedule, safety rules, staff training, and incident records match the real operation.
Workers compensation is one example. Premiums commonly start with the work being classified and the payroll attached to that work. Triple-I explains that state, industry, payroll percentage, and a business’s safety record can affect the cost; brokers may also discuss experience rating or claims history when they review the account. When a venue moves from owner-operated weekends to daily paid attendants, party hosts, cleaners, and cafe staff, the payroll exposure changes.
Finance teams should budget the premium beside opening cash, not after it. SBA startup-cost guidance includes insurance, licenses and permits, equipment, employee salaries, advertising, utilities, and professional help in the planning categories, and it separates one-time and monthly costs. That structure fits an indoor playground because the opening budget and monthly operating budget can fail in different places.
Equipment Documentation Can Change the Underwriting Conversation
Equipment paperwork does not guarantee a lower premium, but it can keep the quote conversation from stalling. An underwriter may ask for attraction lists, equipment drawings, manufacturer details, safety standards, maintenance routines, incident reporting, staff training, waivers, and certificates of insurance for parties that need to be named.
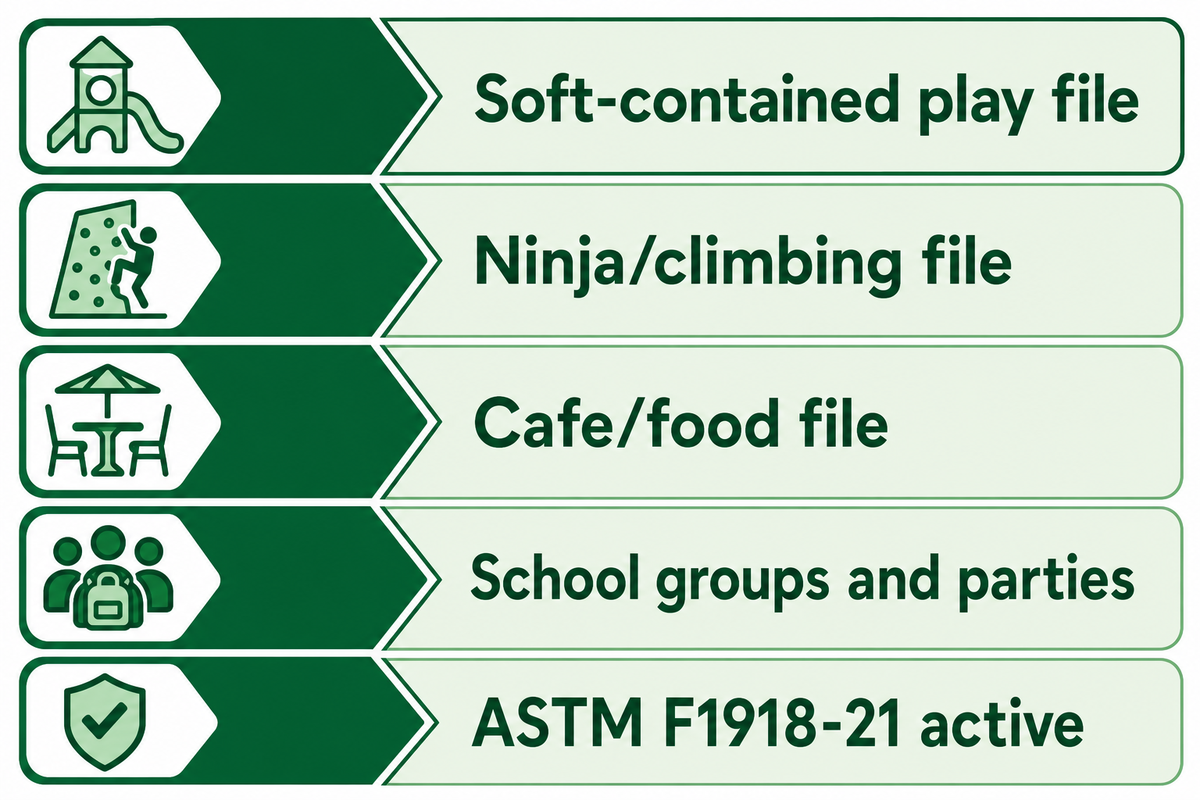
For soft-contained play, the official ASTM public listing identifies ASTM F1918-21 as the active Standard Safety Performance Specification for Soft Contained Play Equipment. That listing describes a user range from younger children through preteens and separates soft-contained play from public playgrounds, home playgrounds, sports equipment, amusement rides, unrelated fitness equipment, water attractions, toys, and juvenile products.
Attraction or exposure
File to prepare
Why it matters
Soft-contained play
Layout, age range, safety standard discussion, inspection routine
Confirms the quoted risk is soft play, not an excluded attraction type
Ninja or climbing
Element list, fall zones, supervision plan, training log
Shows how higher-movement attractions are controlled
Cafe or food service
Food permit, vendor list, cleaning process, staff role split
Separates premises risk from food-service exposure
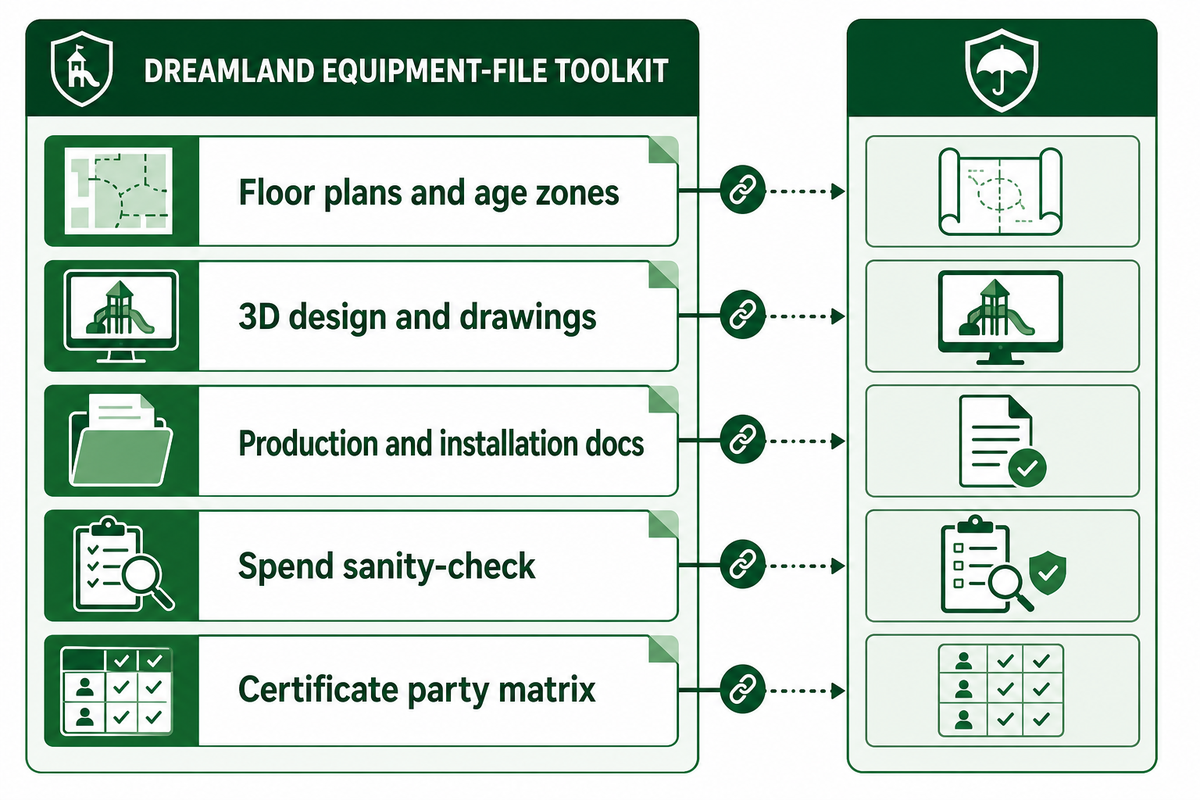
Dreamland’s role is equipment and project support. For insurance cost planning, that role is useful when the owner needs a clear equipment file before a broker submits the application. Dreamland can help organize floor plans, age zones, attraction lists, equipment drawings, 3D design details, production records, shipping information, and installation support documents from the project side.
Start with the equipment file before the insurance quote
Send your floor plan, ceiling height, target age group, attraction list, market, theme, and opening timeline. Dreamland Playground can prepare a layout concept and equipment quote that makes the insurance application easier to describe.
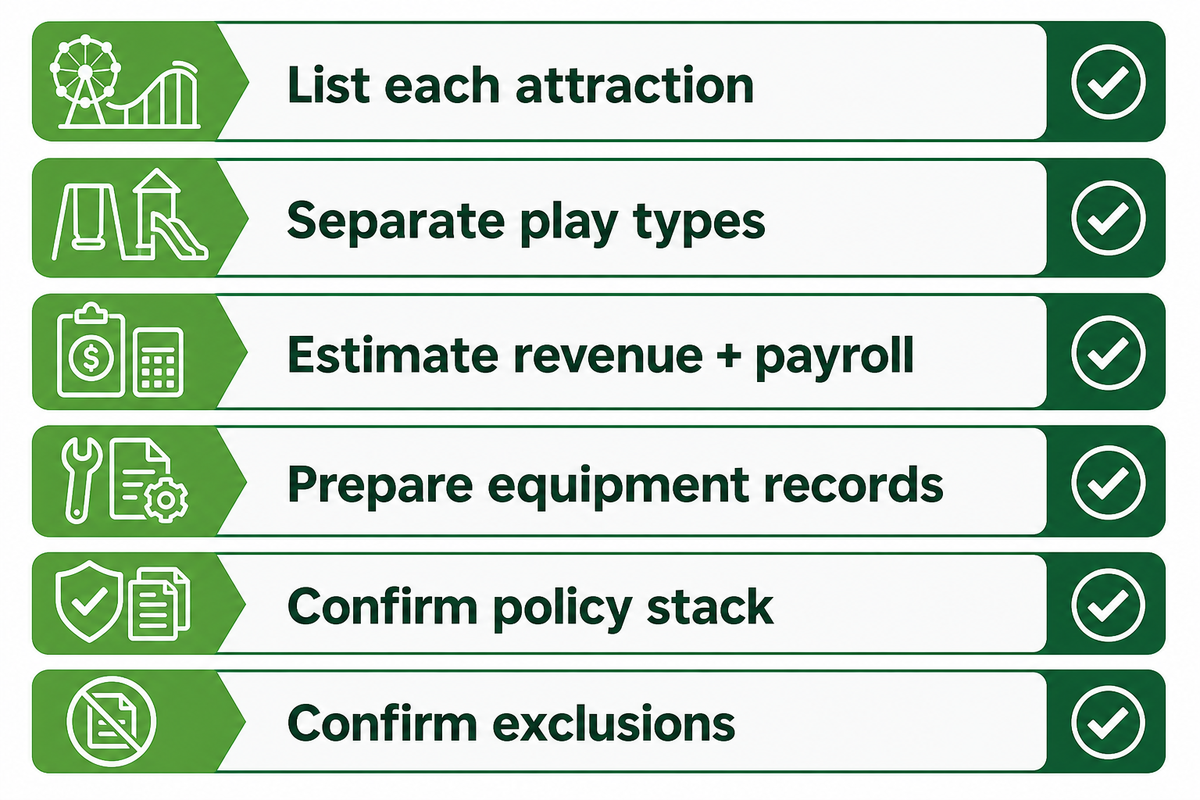
Before owners compare premium totals, they should make sure each quote is pricing the same venue, attraction list, policy stack, payroll assumption, and certificate requirement. A cheaper policy is not comparable if it excludes the activity that drives the real loss exposure.
List each attraction exactly as it will appear on the floor.
Separate soft play, ninja, climbing, trampoline, arcade, cafe, party rooms, and mobile or event use.
Estimate annual revenue, daily visitor count, payroll, and seasonal staffing.
Prepare equipment value, replacement cost, maintenance logs, staff training records, and incident report workflow.
Ask whether the quote includes general liability, property/BOP, workers compensation, umbrella, auto, cyber, and any special endorsement.
Confirm exclusions before comparing price. Cheaper policies that exclude the real attraction don’t transfer the real risk.
Frequently Asked Questions
What kind of insurance do I need for an indoor playground?
Indoor playgrounds usually start with general liability, property or BOP coverage, and workers compensation when employees are hired, then review umbrella coverage and endorsements for attractions, food service, events, or off-site use.
Most venues also review umbrella or excess liability, commercial auto, cyber coverage, event coverage, and endorsements for food service, trampolines, climbing, ninja elements, or off-site events. The right stack depends on the attraction list, employee count, landlord limits, state workers compensation rules, and whether parties or school groups are part of the operation.
Is $3,000 a year enough for indoor playground insurance?
A $3,000 annual premium may be enough for a small, lower-risk play cafe in some cases, but it is not a safe assumption for every indoor playground or family entertainment center.
Insureon’s public baseline for three common policies totals $2,184 a year before higher limits, property value, umbrella coverage, attraction risk, revenue, payroll, state rules, and claims history are added. Dreamland’s estimated $3,000 to $6,000 band is a pre-quote planning range for a lower-risk soft-play cafe, not a published carrier figure. Before relying on it, check the attraction list, landlord limits, staff count, food-service exposure, and state workers compensation rules with a licensed broker.
Why is family entertainment center insurance more expensive?
A larger family entertainment center usually has more visitors, more staff, higher equipment value, food or party exposure, and more attraction types, so the policy must price a broader operating risk.
Premiums can rise when the venue adds ninja lanes, climbing, trampolines, cafe service, school groups, party bookings, arcade areas, or higher liability limits. Underwriters also review attraction schedules, staff training, incident reports, waivers, maintenance logs, claims history, visitor volume, payroll, and whether each high-motion attraction is clearly included in the policy wording.
Can better equipment documents lower my premium?
Better equipment documents do not guarantee lower premiums, but they can make the underwriting file clearer by showing the attraction mix, age zones, maintenance routine, safety standards, and supervision plan.
Clean files help brokers describe the real attraction mix instead of letting the carrier assume the worst version of the category.
This article uses public insurance cost pages, standards summaries, and Dreamland’s equipment-file tools to build a planning model for indoor playground insurance cost. The annual dollar bands are Dreamland planning ranges, not published carrier data. Final premiums must come from a licensed insurance broker or carrier because facility location, revenue, payroll, attractions, claims history, and policy wording can change the result.
Dreamland Playground publishes practical planning guides for commercial indoor-play projects, including family entertainment centers, shopping malls, hotels, restaurants, churches, and other venue types.
Use these guides to frame the questions that should be resolved before concept selection: venue size, intended age groups, project location, attraction mix, operating priorities, timeline, and delivery constraints. Final recommendations should be based on the real site and applicable local requirements.
Start With The VenueFloor area, clear height, site location, intended audience, and target opening date create the working brief.
Clarify The ScopeConcept, equipment, production, shipping, installation, and operating inputs can vary from one project to another.
PROJECT / VENUE / TIMELINE
Prepare Your Project Brief
Venue TypesFEC · Mall · Hotel · Restaurant · Church
Start WithFloor area · Clear height · Age groups · Country